What Does a Forex Turnkey Solution Include? Full Scope
Quick answer
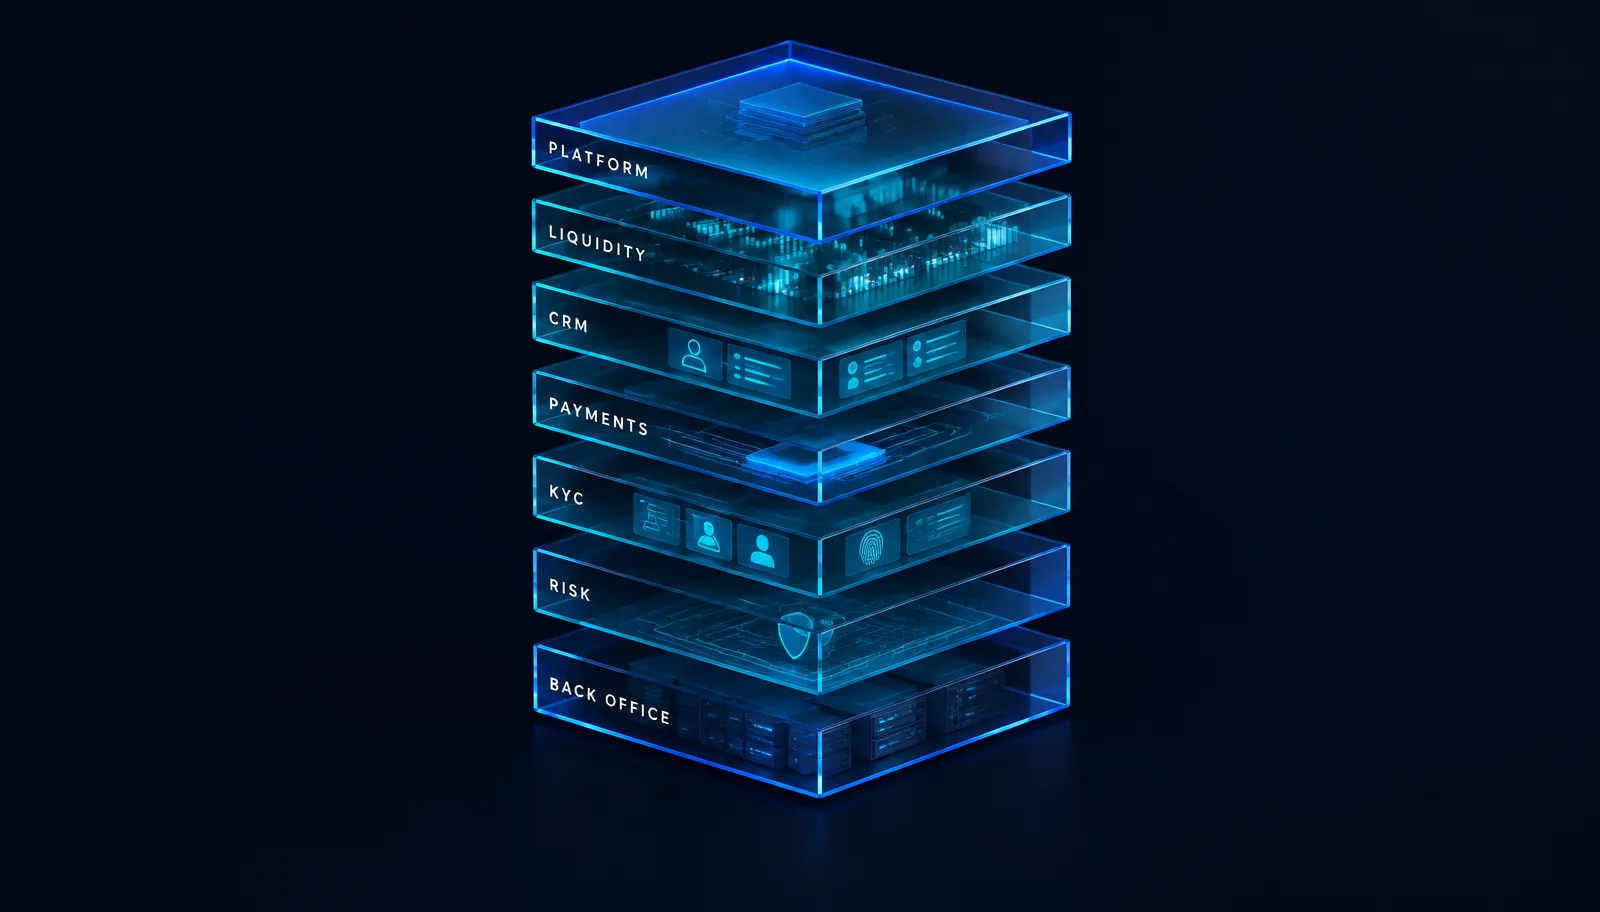
A forex turnkey solution should deliver every layer a brokerage needs to accept a client, price a trade, settle money, supervise exposure and keep operating: corporate and jurisdictional structuring, banking and payment infrastructure, a trading platform with liquidity and a bridge, a CRM and client cabinet with partner infrastructure, risk oversight, and an engineering path for integration and scale. Anything narrower is a starter kit, not a brokerage.
Contents
- What turnkey is not
- Layer 1 — Establish
- Layer 2 — Connect
- Layer 3 — Trade
- Layer 4 — Operate
- Layer 5 — Protect
- Layer 6 — Scale
- Turnkey vs white label
- What to ask before choosing a provider
- Decision checklist
- FAQs
What turnkey is not
The most expensive assumption in this market is that a brokerage is an incorporated company plus a website plus a MetaTrader server. Those three things can be assembled in weeks and still leave a business unable to onboard a client legally, receive a deposit reliably, price a symbol competitively or explain its exposure to a counterparty.
Turnkey should mean the opposite: the operating layers are joined up, so a lead entering at the top of the funnel reaches a funded, supervised trading account without a manual handover between disconnected systems. It is useful to read the scope as six layers, because each one has its own vendors, its own failure modes and its own ongoing cost.
Layer 1 — Establish
Before technology, the commercial model has to be decided, because almost everything downstream inherits from it. Whether you intend to run A-Book, B-Book or a hybrid book changes your liquidity relationships, your risk tooling and your capital planning. Whether you sell primarily through partners changes your CRM and commission requirements. Whether you target retail clients in regulated markets changes your structuring entirely.
This layer covers business-model definition, corporate structuring, choice of jurisdiction, and the authorisation pathway where a licence or registration is required for your intended activity and client base. Two points deserve emphasis. First, incorporating a company is not the same as being authorised to conduct regulated investment activity — they are separate processes with separate requirements. Second, jurisdiction selection is not a shopping exercise for the lightest requirement; it interacts with banking access, payment-provider appetite, platform licensing and the markets you can realistically address. Structuring decisions of this kind belong in a conversation with qualified legal advisers in the relevant jurisdiction.
Layer 2 — Connect
Money movement is where new brokerages most often stall. A trading business needs somewhere to hold operating and client funds, a route for clients to deposit in the currencies and methods their market actually uses, and a controlled withdrawal process.
- Banking strategy. Corporate accounts, operating accounts, segregation arrangements where required, and a realistic view of onboarding timelines and documentation.
- Payment service providers. Card acquiring, local transfer rails, e-wallets and regional methods, selected by target market rather than by convenience. Coverage gaps show up as approved clients who never fund.
- KYC and AML tooling. Document verification, sanctions and PEP screening, risk classification and periodic re-verification, with the decision and its evidence stored against the client record.
- Payment operations. Deposit crediting, withdrawal approval, reconciliation of unmatched references, chargeback handling and reporting.
The engineering half of this layer is integration: payment confirmations have to reach the client record and the trading account without a person retyping anything. That is the work covered by banking and PSP integration.
Layer 3 — Trade
This is the layer most people mean when they say turnkey, and it has four distinct parts.
- Trading platform. MetaTrader 5, MetaTrader 4 where still relevant, cTrader or a proprietary front end — plus the server-side configuration that decides how your business actually behaves: groups, symbols, leverage tiers, margin rules, swaps, commissions and trading sessions. See trading platforms.
- Liquidity. Pricing relationships appropriate to your instruments, volumes and client profile, with attention to spread quality, depth, fill behaviour and cost structure rather than headline spreads alone. See liquidity.
- Bridge and gateway. The layer that aggregates price sources, builds your books, applies markup and routing rules, and passes orders to counterparties with A-Book, B-Book or hybrid handling. See bridge and gateway.
- Hosting and connectivity. Where the platform and bridge run, proximity to liquidity venues, redundancy, monitoring and backup. Latency is an architecture decision, not a setting.
Layer 4 — Operate
A brokerage that can trade but cannot administer itself will consume its margin in manual work. The operating layer is the daily business.
- Forex CRM. The system of record for leads, clients, KYC state, documents, trading accounts, transactions and partner relationships — see Forex CRM.
- Client cabinet. Registration, verification, funding, withdrawals, account management and reporting in the client-facing portal.
- IB and partner infrastructure. Referral tracking, multi-level hierarchies, commission calculation, partner statements and payout workflow.
- Platform administration. Ongoing group, symbol, leverage and margin management, and the operational discipline around changes — see platform administration.
- Reconciliation and reporting. Matching platform balances against payment records, and producing management and regulatory reporting from data you can defend.
Layer 5 — Protect
Risk oversight is not a later phase. A brokerage carries exposure from its first funded account, and the tooling and coverage decisions have to exist before volume arrives.
- Risk management software. Consolidated exposure by symbol, group and client, position and margin monitoring, and configurable alerting — see RiskMan.
- Dealing coverage. Who watches the book outside your office hours, what they are authorised to do, and how escalation works — see 24/7 dealing desk and risk management.
- Risk workflows. Written policy for exposure limits, client classification, toxic-flow handling and routing changes, so decisions are consistent and reviewable rather than improvised.
Layer 6 — Scale
The final layer is what separates a launch from a business that can still change two years later: API access and integrations for internal tools and third-party systems, custom development where your model differs from the standard, a migration path if you inherit a platform or CRM, and access to people who have operated brokerages when you need an operational opinion rather than a support ticket.
Turnkey vs white label
The terms are used loosely, so define them in the contract rather than in the brochure.
| Dimension | White label | Turnkey |
|---|---|---|
| What you get | Branded access to another firm''s platform environment | Your own operating stack across establish, connect, trade, operate, protect, scale |
| Server control | Usually a group on the provider''s server | Typically your own environment and configuration |
| Liquidity relationship | Often via the provider | Direct or arranged, with visibility of terms |
| Client ownership and data | Can be shared or constrained | Yours, in systems you control |
| Risk model | Frequently limited by the host | A-Book, B-Book or hybrid by your own design |
| Speed to market | Faster | Longer, with more capability at the end |
| Best for | Testing a market or a distribution-led start | Operators intending to run and grow a brokerage |
White label is a legitimate starting point. The mistake is choosing it while planning to behave like a full brokerage, then discovering that pricing, risk handling and client data are all constrained by somebody else''s environment.
What to ask before choosing a provider
Most turnkey disappointments trace back to scope that was never written down. Ask specifically:
- Which of the six layers are in scope, and which are referrals to third parties?
- Who owns the trading server, the CRM database and the client data?
- Which liquidity and bridge arrangements are proposed, and can we see the routing and markup logic?
- What exactly is configured at handover — groups, symbols, leverage, margin, swaps, commissions — and who changes them afterwards?
- How do the CRM, trading platform and payment providers integrate, and what happens when one of those integrations fails?
- What risk tooling and dealing coverage is included, and what is the escalation path outside office hours?
- What are the ongoing costs: licensing, hosting, support, per-account and per-transaction charges?
- What are the support hours, response commitments and escalation contacts?
- What does exit look like — can we migrate the platform, CRM and client data elsewhere?
- Which parts of the engagement depend on decisions only our legal advisers or regulator can make?
Decision checklist
| Layer | Confirm before signing | Red flag |
|---|---|---|
| Establish | Business model, structure and authorisation pathway defined with qualified advisers | Incorporation presented as equivalent to authorisation |
| Connect | Banking route and market-appropriate payment methods identified; KYC tooling selected | Payments treated as something to solve after launch |
| Trade | Platform, liquidity, bridge and hosting specified with configuration documented | Headline spreads quoted with no view of fills or depth |
| Operate | CRM, cabinet, IB infrastructure and platform administration integrated | Onboarding steps completed by staff moving data between systems |
| Protect | Exposure monitoring, alerting and out-of-hours coverage in place from day one | Risk described as a later phase |
| Scale | API access, migration path and development capacity available | No supported interface and no exit route |
Sequencing: what has to be decided before what
Turnkey programmes fail on order as often as on scope. Some decisions constrain everything after them and cannot be revisited cheaply.
- Model and market first. A-Book, B-Book or hybrid, and the countries you intend to serve. These determine liquidity relationships, risk tooling, payment coverage and structuring.
- Structure and authorisation next. Jurisdiction and authorisation pathway drive banking appetite, payment-provider onboarding and what you may say to whom.
- Payments in parallel, early. Banking and PSP onboarding is externally paced and routinely the longest item; starting it after the platform is configured is the most common source of delay.
- Platform, liquidity and bridge together. These are one decision in practice — instrument coverage, pricing, routing and risk handling have to agree.
- CRM and operations before launch, not after. Onboarding, funding and partner workflows should be live before real clients arrive, because retrofitting them means migrating client data.
- Risk from the first funded account. Exposure monitoring and out-of-hours coverage are launch requirements, not growth features.
The ongoing cost of ownership
A turnkey quote is a starting position. What decides the economics is the recurring column: platform licensing and per-account charges, hosting and connectivity, liquidity and bridge fees, payment costs by method and region, CRM and module licensing, risk tooling and dealing coverage, support, and the internal headcount each layer still requires. Ask for that breakdown in writing before comparing providers, because two identical launch prices can carry very different monthly obligations.
Comparing turnkey quotes: a buyer's checklist
Two turnkey proposals can differ by a factor of three in price while both claim to include "everything". The comparison only makes sense layer by layer. For each quote, mark which of the six layers above is actually covered, then ask:
- Whose name is on each contract? Platform licence, PSP agreements, KYC vendor, hosting. Contracts in your entity's name survive a provider change; contracts nested under the provider do not.
- What is explicitly excluded? Licensing legal fees, PSP reserves, bridge setup, market data fees and support tiers are the most common exclusions. Get the exclusions list in writing.
- Who operates what after launch? A turnkey build is not a turnkey operation. Define the boundary: who handles deposit exceptions, withdrawal approvals, platform maintenance and incident response.
- What does leaving look like? Ask for a sample data export and the exit terms before signing, not after. Our 20-question provider checklist covers ownership, technical, operational and exit questions in full.
- Which components are the provider's own, and which are resold? Neither answer is wrong, but you should know which layer you could replace without replacing everything.
For the underlying architecture each layer plugs into, see the broker technology stack guide.
FAQs
Is a turnkey brokerage the same as a licensed brokerage?
No. A turnkey programme can build the corporate, technical and operational stack and support an authorisation process, but being licensed or registered is a regulatory outcome determined by the relevant authority, not something a technology provider can deliver.
How long does a turnkey launch take?
It depends on jurisdiction, banking and payment onboarding, licensing route and how much configuration your model needs. Timelines that ignore third-party approvals should be treated with caution, and we do not publish a fixed launch guarantee.
What does it cost?
Cost varies with jurisdiction, platform licensing, liquidity arrangements, module scope and hosting, so it is scoped per engagement rather than listed publicly. What matters when comparing quotes is which of the six layers each price actually covers.
Can we start narrow and add layers later?
Yes, and many operators should. The requirement is that early choices — platform environment, CRM data model, payment integration, risk tooling — do not make later layers impossible without a migration.
Where this sits in our work
InfyTradeTech delivers these layers as one programme rather than as separate purchases, which is the point of turnkey. If you are evaluating scope, the commercial detail sits on our Forex turnkey solutions for brokers page.
Related Research
Operator-level analysis supporting forex broker turnkey solutions.
Take this from research to build.
Our team builds and operates forex broker turnkey solutions for brokers and prop firms.