Forex Liquidity & Execution Infrastructure
Aggregate several liquidity sources and route execution through one architecture — connected to MT4/MT5, cTrader or Match-Trader through OneZero, Centroid, PrimeXM or your existing bridge, with routing rules your risk team controls.
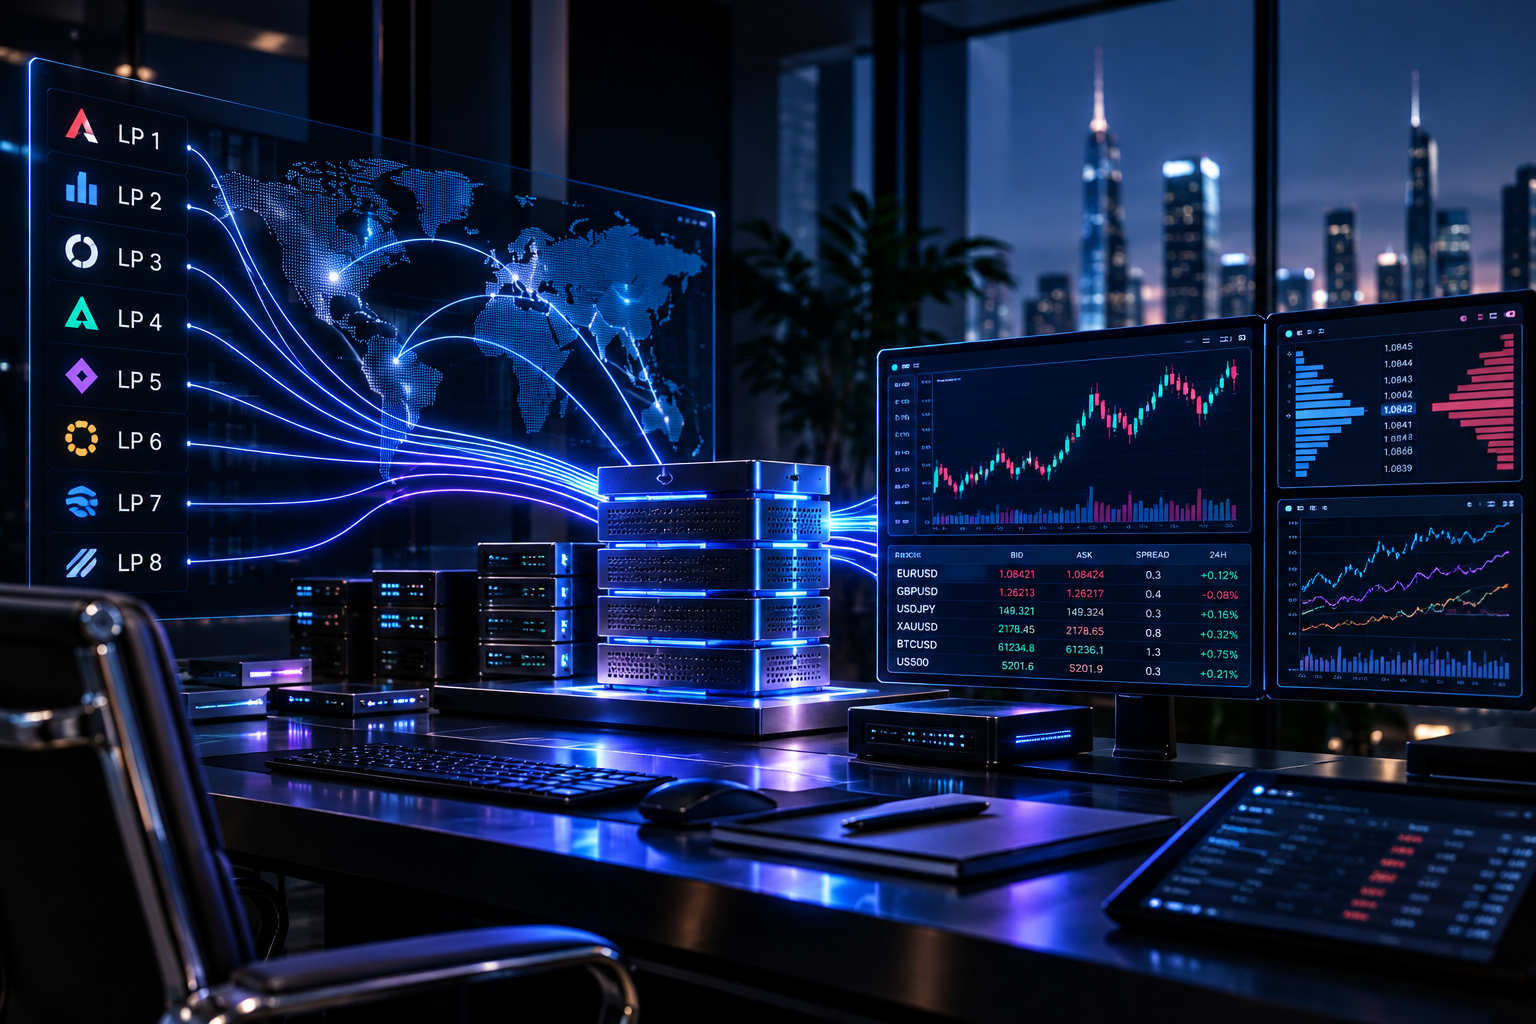
How liquidity is aggregated and routed
Prices move from LPs through an aggregator and bridge to your platform. Orders travel back through routing rules that decide A-book, B-book or hedge. Select a flow to trace it.
Price aggregation
- 1Each LP streams quotes over its own FIX session
- 2The aggregator normalises symbols and builds a combined book
- 3Best available bid and ask are passed to the bridge
- 4The bridge applies symbol mapping and markup, then publishes to the platform
Order routing
- 1A client order arrives from the trading platform
- 2The bridge checks routing rules: client group, symbol, volume
- 3Eligible flow is sent on the A-book route
- 4The aggregator fills against the selected LP and returns the execution report
Hybrid A/B-book
- 1Flow outside A-book rules is internalised on the B-book
- 2RiskMan aggregates resulting net exposure per symbol
- 3A breached exposure threshold raises a hedge trigger
- 4Hedge orders or rule changes are applied through the routing layer
LP failover
- 1One LP session drops or its quotes go stale
- 2The aggregator removes that stream from the combined book
- 3Pricing continues from the remaining connected LPs
- 4The session is re-admitted after it reconnects and passes checks
Reference architecture. LP panel, bridge vendor and routing rules are selected per broker; the execution model (A-book, B-book or hybrid) remains the broker's decision.
Real Liquidity Problems We Solve Every Week
The four scenarios below cover most briefs we receive for liquidity engagements. If any of these describe you, we can scope the work after a short discovery call.
Your current LP shows wide spreads at news, frequent rejections and slippage you cannot explain to clients.
We review execution reports, define the measurements that matter (effective spread, fill ratio, rejections, latency) and rebuild the LP panel and routing around them.
You want to A-book professional flow and internalise retail flow, but your bridge cannot separate them.
Routing rules are configured by client group, instrument and volume, so the execution model becomes a documented policy your risk team owns.
You have outgrown a single LP, but direct prime-broker relationships are out of reach for your entity today.
We assess prime-of-prime and multi-LP options against your entity, jurisdiction, instruments and expected flow, and plan a path to direct relationships later.
A white-label feed is marketed as Tier-1, but you cannot see who is actually filling your orders.
We ask for named counterparties, agreements and execution data before onboarding, and favour transparent relationships held in your company's name.
Liquidity Source Types
The panel is designed per instrument and client segment from the source types available to your entity.
Bank liquidity
Bank market-maker pricing, usually accessed through a prime broker or prime-of-prime intermediary, for FX majors and minors.
Non-bank market makers
Electronic market makers that stream firm pricing and can complement bank liquidity across sessions and instruments.
Prime-of-prime
A single counterparty that provides access to aggregated institutional liquidity, commonly used by brokers before direct prime relationships.
CFD, index and commodity feeds
Pricing for index, equity, energy and metals CFDs from providers that support those products for the broker's entity.
Digital-asset liquidity
Where the licence and product scope allow it, spot or derivative digital-asset pricing connected through the same bridge or kept segregated.
Aggregated Feed vs. The Alternatives
A vendor-neutral view of the common liquidity models and when each fits.
| Model | LPs | Execution | Collateral | Best For |
|---|---|---|---|---|
| Multi-LP aggregation | Several, configurable | Routed by rules | Per LP / prime agreement | Brokers wanting depth and redundancy |
| Single prime-of-prime | One counterparty | Provider-dependent | Single agreement | Brokers launching with simple operations |
| Direct prime broker | Prime + its panel | Institutional | Highest, entity-dependent | Established, well-capitalised brokers |
| White-label LP feed | Vendor-defined | Check for internalisation / last-look | Lower | Only with full counterparty transparency |
| Self-built aggregation | Whatever you connect | Build-dependent | Per LP | Teams with in-house engineering |
Execution quality and collateral depend on volume, jurisdiction, entity and the chosen LP panel; we assess them in the liquidity audit.
For firms building the complete brokerage environment rather than liquidity alone, this layer is normally scoped inside an end-to-end Forex Turnkey Solution, so LP selection, bridge configuration and risk policy are decided together instead of in sequence.
Liquidity Engagement Scopes
Three common starting scopes. Final scope, timeline and commercials are confirmed after the liquidity audit.
Single-LP Setup
One liquidity relationship connected to your platform.
- One LP or prime-of-prime relationship
- Bridge or native connector configuration
- Symbol mapping and markup setup
- Execution reporting
- Upgrade path to aggregation
For brokers launching with a focused instrument range.
Request a Liquidity ProposalMulti-LP Aggregation
Several LPs combined behind one routing layer.
- Several aggregated LP sessions
- OneZero, Centroid, PrimeXM or comparable bridge
- Hybrid A/B-book routing rules
- LP failover behaviour
- Execution-quality reporting
For brokers needing depth, redundancy and segment-based routing.
Request a Liquidity ProposalCustom Liquidity Design
Bespoke pools, FIX API access and advanced flow handling.
- Custom pools per instrument or segment
- Dedicated bridge instance
- FIX API connectivity
- Hedging and exposure integration
- Periodic LP performance review
For higher-volume brokers and prop firms with custom flow requirements.
Request a Liquidity ProposalLiquidity Onboarding Stages
Legal, technical and operational tracks run in parallel where dependencies allow.

Liquidity audit
Review current LPs, instruments, flow profile, execution model and complaints. Output: a written gap analysis and recommended LP panel.
LP selection & terms
Shortlist LPs matched to entity, jurisdiction, instruments and flow, and review spreads, commission, collateral and service terms.
Legal & counterparty onboarding
Counterparty agreements, KYC packs and collateral funding with each LP; FIX credentials issued.
Bridge & routing configuration
Bridge connected to the LP panel; symbol mapping, markups, routing rules, hedge triggers and exposure limits configured.
UAT & parallel run
Demo server connected to live pricing; spread, slippage and rejection behaviour measured before a controlled production run.
Cutover & tuning
Production cutover, then LP weights, markups and thresholds tuned using real flow data.
What You Need to Provide
A complete kickoff pack keeps counterparty onboarding moving. Start gathering these once the engagement is signed.
Kickoff Pack
- Brokerage licence certificate
- Financial statements (if available)
- Director KYC pack (passports, addresses, CVs)
- Beneficial owner declarations
- AML / CFT policy document
- Source of funds / capital declaration
- Current LP statement (volumes, spreads)
- Trading platform details (MT4/MT5/cTrader)
- Bridge in use (or 'need recommendation')
- Instrument wishlist with minimum specs
- A/B-book strategy by client segment
- Target collateral / funding amount
- Risk officer contact details
- Reference letters (banking, audit, legal)

Ongoing Liquidity Optimisation
Onboarding is the start, not the finish. Our managed-services wrap continuously tunes spreads, fill rates, and risk routing as your business evolves.
Execution quality monitoring
Reporting on effective spread, slippage, fill ratio and rejections per LP and client segment, with underperforming sessions flagged for review.
Markup & commission review
Periodic review of markup and commission structure against client behaviour and competitiveness.
Risk-book health checks
Review of A/B-book exposure, hedge effectiveness and concentration, with actions agreed with your dealing and risk teams.
LP renegotiation
Commercial terms reviewed with updated volume and execution data against the original agreements.
New instrument roll-out
Sourcing pricing for new symbols, configuring the bridge and releasing them to production.
Incident coordination
When an LP session degrades, we coordinate with the provider and document cause and remediation, within the agreed support scope.
Common LP Pitfalls We Pre-Empt
Recurring mistakes in LP setups, and how we address them during the audit and bridge design.
Believing 'Tier-1' marketing
Some white-label feeds are a vendor's own book presented as Tier-1. Ask for named counterparties, agreements and execution data before you sign.
Over-aggregating too early
Connecting many LPs before you have the flow leaves inactive sessions and weak commercial terms. Start small and add LPs as volume justifies it.
Ignoring collateral mechanics
Collateral requirements move with your hedge book. Model margin buffers before launch, not after the first margin call.
Last-look on retail flow
Last-look lets an LP reject orders after seeing the price move. Understand each LP's execution terms and how they affect your clients.
B-book without a hedge plan
Internalised flow needs exposure limits and hedge triggers. Configure them in the routing layer from day one.
An Independent Liquidity Architect
Multi-platform experience
LP connectivity across MT4, MT5, cTrader, Match-Trader and proprietary platforms.
Vendor-neutral
LP and bridge recommendations follow your entity, flow and execution model, not a preferred-vendor list.
Operator background
Our team has run dealing desks and risk books, so routing is designed the way operators need it.
Complete Your Brokerage Stack
Liquidity Provider Solutions — Your Questions Answered
Get a Free Liquidity Audit
Tell us about your current setup and we'll send a tailored proposal — recommended LP panel, expected spreads, latency benchmarks, and onboarding timeline — within 24 business hours.
Or email hello@infytradetech.com
Explore Related Solutions
Explore Liquidity Research
Operator-level analysis supporting liquidity & execution.