Forex Broker CRM: What a Modern Brokerage Actually Needs in 2026
Quick answer
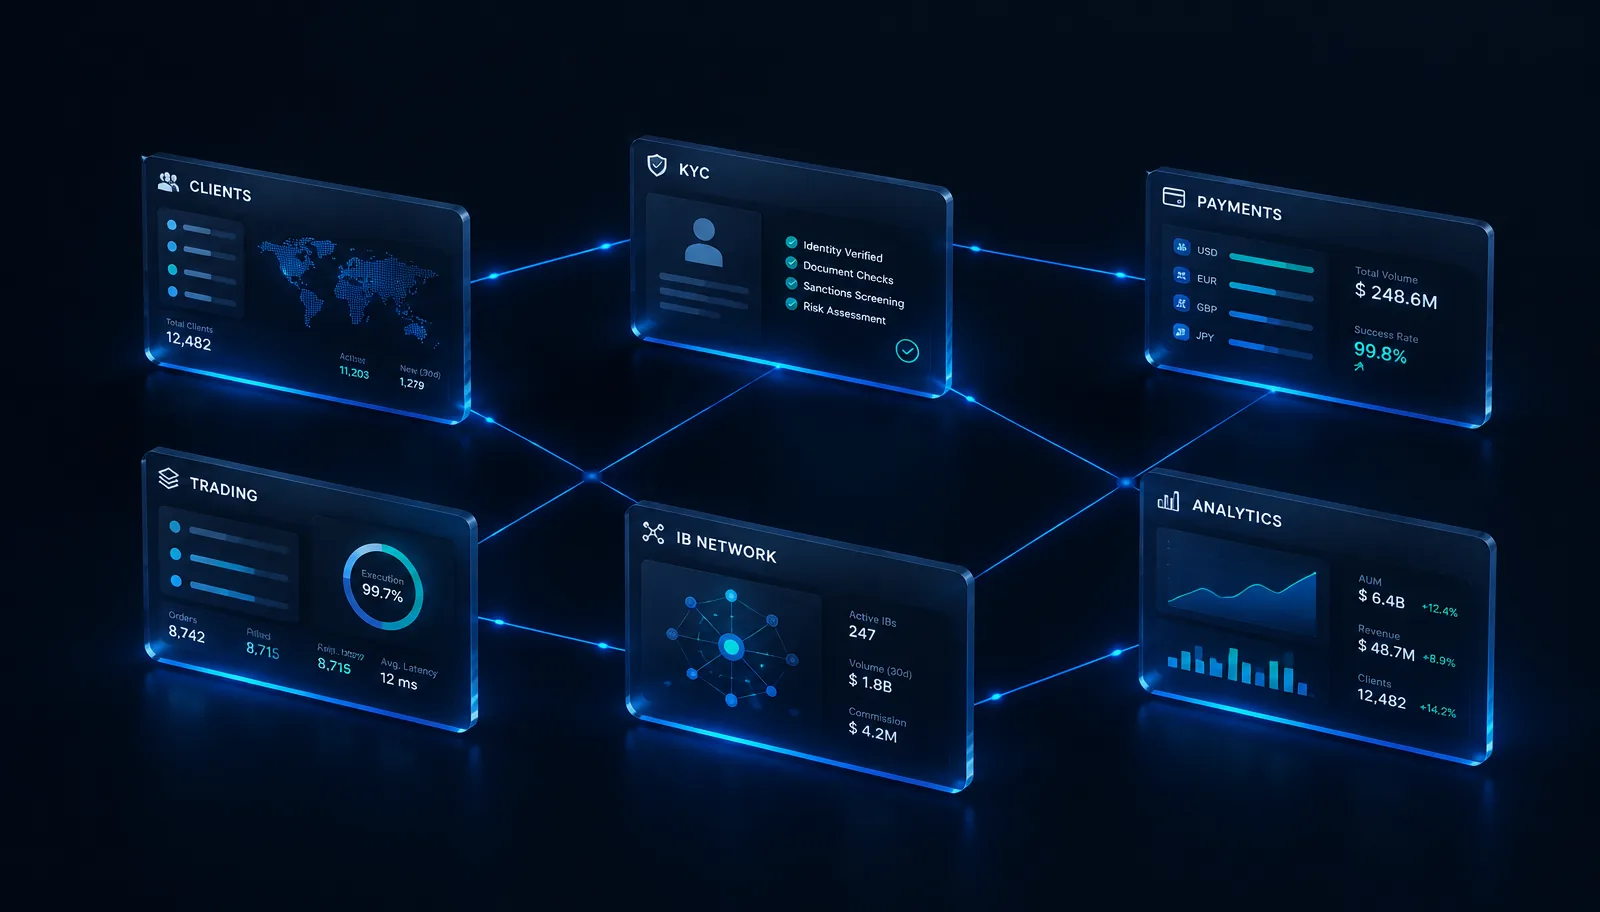
A generic CRM is built around a deal that closes. A forex CRM is built around a client who is verified, provisioned with trading accounts on a platform server, funded through payment providers, attributed to a partner hierarchy and supervised for the rest of their lifecycle. The difference is not a feature gap you can plug with integrations; it is a difference in the data model.
Contents
- Where generic CRM genuinely works
- Where generic CRM starts breaking down for brokers
- Why the trading account changes the architecture
- Capability comparison
- Why IB infrastructure matters
- The integration argument, examined honestly
- When should a brokerage replace its generic CRM?
- FAQs
Where generic CRM genuinely works
General-purpose CRMs are strong products, and it is worth being precise about what they do well, because plenty of brokerages keep using them for exactly those things. They are good at contact management, pipeline and task management, sales-team performance, marketing-campaign tracking, email sequencing, call logging and reporting on conversion between sales stages.
If your business is early, your onboarding is still manual by choice, and your primary question is whether your sales process converts, a general CRM will answer that. Many firms also keep one alongside a brokerage system for institutional or partner business development, where the object really is a deal with stages.
Where generic CRM starts breaking down for brokers
The strain appears at the moment a lead stops being a sales prospect and becomes a regulated, funded client. Four things happen that a deal-centric model was never designed for.
- Verification becomes a stateful process. KYC is not a checkbox. It is documents with types, versions and expiry dates; screening results; a reviewer; a decision; and evidence for that decision that has to survive an audit years later.
- One client becomes many accounts. Live and demo, different groups, leverage tiers, base currencies and statuses. A single record with custom fields cannot represent that cleanly, and reporting degrades immediately.
- Money becomes a ledger. Deposits, withdrawals, internal transfers and adjustments, each with a provider reference and a state that has to reconcile against platform balances.
- Relationships become hierarchical. Partner attribution runs through master IBs and sub-IBs, with ownership dates and commission plans that feed calculations, not notes.
The visible symptoms are familiar: staff creating trading accounts by hand in the platform administrator, spreadsheets used to calculate partner commissions, deposits confirmed in one system and credited manually in another, and nobody able to say confidently how many approved clients never funded last month.
Why the trading account changes the architecture
In a generic CRM the central object is an opportunity: it moves through stages and then closes. In a brokerage the central object is the trading account, and it never closes. It has a platform login, a group, leverage, a base currency and a status; it holds a balance and equity that live on the trading server; it generates activity that drives both retention and commission; and it must be created, modified and eventually archived in two systems at once — the CRM and the platform.
That two-system relationship is the architectural crux. Provisioning has to be transactional and observable: if a client is approved in the CRM, an account must exist on the server, and if it does not, that must be an alert rather than a silent gap. On MetaTrader 5 this is the work of the MT5 Manager API, operating against the group and symbol structure maintained through platform administration. A CRM that treats the platform as an occasional data import cannot own this.
Capability comparison
| Capability | Generic CRM | Forex CRM |
|---|---|---|
| Lead management | Yes, and often very good | Yes, with brokerage-specific source and IB attribution |
| KYC workflow | Usually a third-party integration or custom fields | Built into the client lifecycle with documents, decisions and evidence |
| Trading accounts | No native concept | A core operational entity, many per client |
| MT5 / platform integration | Custom development | Purpose-built provisioning and synchronisation |
| Deposits and withdrawals | Not native | Brokerage workflow with approval and reconciliation states |
| IB portal | Usually absent | Core capability |
| Multi-level IB | Usually absent | Supported hierarchy architecture |
| Commission engine | Custom build | Broker-specific calculation against activity and hierarchy |
| PSP integration | Generic payment links | Brokerage funding workflow with crediting and matching |
| Account provisioning | No | Yes, driven by verification and policy |
| Trading activity and status | No | Operational data used for retention, risk and commission |
| Reporting | Sales-pipeline oriented | Brokerage-oriented: funnel, funding, activity, partners |
Why IB infrastructure matters
Partner distribution is not a marketing detail in this industry; for many brokerages it is the primary acquisition channel. That makes attribution a system requirement rather than a report. The client has to be tied to the correct partner at first touch, the relationship has to survive the client''s entire lifecycle, and commission has to be calculated from real trading activity against a defined plan and hierarchy.
A generic CRM can store a referrer field. What it cannot do is allocate commission through a multi-level hierarchy, produce partner statements that reconcile, track payout status and leave an audit trail for a disputed figure. Once partners are material to revenue, spreadsheet commission becomes both an operational risk and a partner-trust problem. The architecture behind this is covered in our article on forex IB management.
The integration argument, examined honestly
You can integrate a generic CRM towards this. Some firms do it well, and it is a reasonable choice where a business has unusual requirements and real engineering capacity. Be clear-eyed about what you are taking on: you are building and then maintaining a trading-account model, platform provisioning and synchronisation, a payment ledger with reconciliation, a commission engine, a client portal and an audit trail — against platform and provider APIs that change.
The honest comparison is not "buy versus build" but "who maintains this in year three". Broker-specific systems exist because that maintenance is continuous, and because the failure modes — an approved client with no account, an unmatched deposit, a miscalculated partner statement — are expensive in trust rather than in engineering hours.
When should a brokerage replace its generic CRM?
Not on principle. Replace it when the operational signals are clear:
- Trading accounts are being created manually, or created in the platform first and reconciled afterwards.
- Partner commissions are calculated outside the system, or partners dispute figures you cannot reconstruct.
- Deposits require staff to move information between the payment provider and the platform.
- You cannot report reliably on the funnel between registration, verification, funding and first trade.
- Compliance requests take days because evidence lives across systems and inboxes.
- Headcount is growing in operations faster than client numbers.
- The verification, funding or partner logic your business needs cannot be expressed in the current model without another custom field.
If two or more of those are true, the constraint is architectural, and more integrations will only distribute the problem. The migration itself is manageable when the target system has a defined model for clients, accounts, transactions and partner relationships to map onto.
The module checklist for 2026
Feature lists obscure more than they reveal, so evaluate a broker CRM by module and by what each module connects to:
| Module | What it must do in 2026 | Connects to |
|---|---|---|
| Lead and sales pipeline | Lead capture from every source, assignment rules, conversion tracking from registration to first deposit | Website forms, ad platforms, telephony |
| KYC workflow | Document collection, verification vendor results, risk scoring, periodic review queues | KYC vendors, back-office approvals |
| Trading account integration | Account creation, balance visibility, group and leverage changes from the CRM with audit | Platform manager API |
| Payments and ledger | Automatic deposit crediting via webhooks, withdrawal queues, per-client ledger, reconciliation exports | PSPs, back office, finance |
| IB and affiliate module | Partner hierarchies, attribution, commission calculation from trade data, partner portal | Platform trade feeds, payout operations |
| Support desk | Tickets linked to the client record, so agents see the same account state the client sees | Client portal, email, chat |
| Automation | Event-driven journeys: onboarding nudges, deposit follow-ups, dormancy reactivation, KYC expiry reminders | Email/SMS providers, portal notifications |
| Reporting and audit | Cross-module reporting, per-action audit trails, regulator- and PSP-ready extracts | All of the above |
If a vendor cannot demonstrate any row live — not in a slide, in a working environment — treat the module as absent.
What changed by 2026
Three shifts separate a 2026 broker CRM from a 2020 one. First, automation became event-driven rather than scheduled: journeys trigger off real events (a failed deposit, a KYC approval, seven days of inactivity) instead of batch campaigns. Second, segmentation moved from static lists to behavioural scoring — our article on AI-assisted client segmentation and retention covers what that looks like in practice, and where its limits are. Third, compliance stopped being a separate system: KYC status, communication consent and audit trails are expected to live inside the client record rather than beside it. A CRM that treats these as add-ons was designed for a different era.
FAQs
Can we keep our generic CRM for sales and use a forex CRM for operations?
Some firms do, particularly where an established sales organisation is attached to the general CRM. It works when one system is unambiguously the system of record for clients, accounts, KYC and money, and the other is treated as a sales tool that reads from it.
Is a forex CRM only for large brokerages?
No. The operational cost of manual provisioning, reconciliation and commission calculation is proportionally heaviest on small teams, which is usually where it is felt first.
What is the hardest part of switching?
Data, not software: mapping historical clients, documents, accounts, transactions and partner relationships accurately, and deciding what is migrated versus archived. Plan the mapping before the timeline.
Does a prop firm need the same thing?
The onboarding half is similar; the middle differs, because challenge accounts, evaluation phases and payouts replace live-account provisioning. That is covered by our prop firm CRM work.
Where this sits in our work
Our Forex CRM is built around the client, trading account, transaction and partner model described above, with optional modules for prop-firm operations and for social and copy trading, and API access where you need to connect your own systems.
Related Research
Operator-level analysis supporting forex crm.
Take this from research to build.
Our team builds and operates forex crm for brokers and prop firms.